CategoriesNews Developments Economy Investment Property Real Estate Investment

As War Grips the Gulf, Pakistani Wealth Flows Back Home

KARACHI: The ongoing Gulf war has significantly disrupted the long-standing flow of undocumented Pakistani wealth into Dubai’s real estate sector, with market sources reporting that funds once considered secure abroad are now being channelled back into property investments within Pakistan.

For years, Pakistan ranked among the top foreign investors in Dubai property, and the emirate was widely regarded as a reliable destination for capital of questionable origin. That dynamic appears to be reversing.

Hassan Bakhshi, Chairman of the All Pakistan Builders Association, estimated that approximately $60 million in undocumented funds had previously left Pakistan for Dubai each month an outflow that has now halted entirely.

Currency market sources describe a similar shift, noting that assets already parked in Dubai have become difficult to liquidate amid the instability caused by the conflict. Rising remittance inflows from the UAE are being interpreted as evidence that Pakistanis are repatriating liquid holdings rather than expanding them abroad.

This capital redirection has had a visible effect on Karachi’s property market. According to Bakhshi, prices in the city’s Defence Housing Authority area have surged by 50 to 60 percent since the war began, driven partly by the area’s reputation for secure property titles.

Other parts of Karachi have seen more moderate gains of 20 to 25 percent, according to property dealer Karim Dad, who attributed the rebound to improved liquidity and government efforts to stimulate the construction sector.

The disruption extends beyond real estate. Several technology firms that previously relocated to Dubai, citing a favourable regulatory climate and frustration with Pakistan’s internet connectivity and tax administration, are now among those seeking to recover stalled investments as the regional situation remains unresolved.

Analysts caution that any large-scale return of capital will likely depend on how quickly stability returns to the Gulf region.

For more real estate news and special reports, visit Chakor.

Sources:
CategoriesReal Estate Investment News Property Laws Property Taxes

FBR Yet to Notify Refund Mechanism for Section 7E, Super Tax Collections

ISLAMABAD: The Federal Board of Revenue (FBR) has yet to establish a mechanism to refund taxes collected under Section 7E, the deemed income tax on immovable property, and Super Tax under Section 4C, despite more than three months having passed since a formal request for such a procedure was made.

Waheed Shahzad Butt, Chairman of the LTBA Public Interest Litigation Committee, said he had written to the FBR Chairman, routed through Board Members, seeking a notified refund process for both levies. He noted that the FBR has not issued any guidance, prescribed an application format, or designated a forum for filing such claims.

The demand follows rulings by the Federal Constitutional Court (FCC), which struck down Section 7E as unconstitutional and void from inception, nullifying all notices and proceedings initiated under the provision. Introduced through the Finance Act 2022, the levy had applied a five percent charge on properties valued above Rs25 million, based on FBR-assessed fair market value.

On Super Tax, the FCC upheld the provision’s constitutional validity but excluded certain exempt capital gains from its scope, meaning the tax cannot be charged on the sale of immovable property held beyond the prescribed holding period, inherited property, or otherwise exempt income.

Butt said the FBR’s continued silence, despite binding constitutional rulings, has left taxpayers in an uncertain legal and financial position. He proposed allowing refunds as an adjustment against tax liability for Tax Year 2026 through the annual return, with field formations directed to process such claims uniformly rather than leaving the matter to individual Commissioners or Regional Tax Offices.

He cautioned that continued inaction exposes the FBR to further litigation, including complaints before the Federal Tax Ombudsman, as affected taxpayers seek redress for amounts they believe were unlawfully retained.

For more real estate news and special reports, visit Chakor.

Source:

CategoriesNews Real Estate Investment

Housing Finance Surges 84% in Approvals as Government Steps Up Access-to-Finance Drive

ISLAMABAD: Federal Finance Minister Senator Muhammad Aurangzeb chaired the fortnightly Access to Finance Steering Committee meeting on Monday, reporting sharp gains across housing, agriculture, SME and export financing since the close of FY26.

Total housing finance climbed from Rs294 billion at end-June to Rs307 billion by mid-August. Under the Wazir-e-Azam Apna Ghar Program, applications rose 52 percent to nearly 139,000, while approvals surged 84 percent to over 46,000, with approved financing nearly doubling to Rs279 billion. Loans disbursed increased 59 percent, crossing Rs38 billion.

The Committee credited the momentum to regulatory reforms, including the State Bank’s revised housing finance rules, a 90:10 loan-to-value ratio and a 65 percent debt-burden ratio, alongside passage of the Financial Institutions (Recovery of Finances) (Amendment) Act, 2026, aimed at strengthening mortgage recovery and lender confidence.

Agriculture borrowers grew to 3.37 million, adding roughly 115,000 since June, with sector financing steady near Rs1.26 trillion. The Zarkhez-e Asaan Zarai Qarza scheme for uncollateralised farm lending recorded over 58,000 registrations.

SME formal financing stood at Rs1.05 trillion across some 330,000 businesses, with a credit-scoring pilot underway across 13 banks. Officials set medium-term targets of Rs1.5 trillion in combined agriculture and SME financing by June 2027, rising to Rs2 trillion by June 2028.

On exports, the newly effective Performance Based Rebate on Incremental Exports offers exporters a 1 percent rebate for growth up to 10 percent, and 2 percent beyond that. The Pakistan Accelerated Vehicle Electrification Programme also gained pace, with EV deliveries tripling to over 1,500 units.

Aurangzeb called for tighter bank-wise monitoring and broader public awareness to sustain credit growth across housing, farming and enterprise sectors.

For more real estate news and special reports, visit Chakor.

Source:

CategoriesNews Economy Property Real Estate Investment Urban Developments & Planning

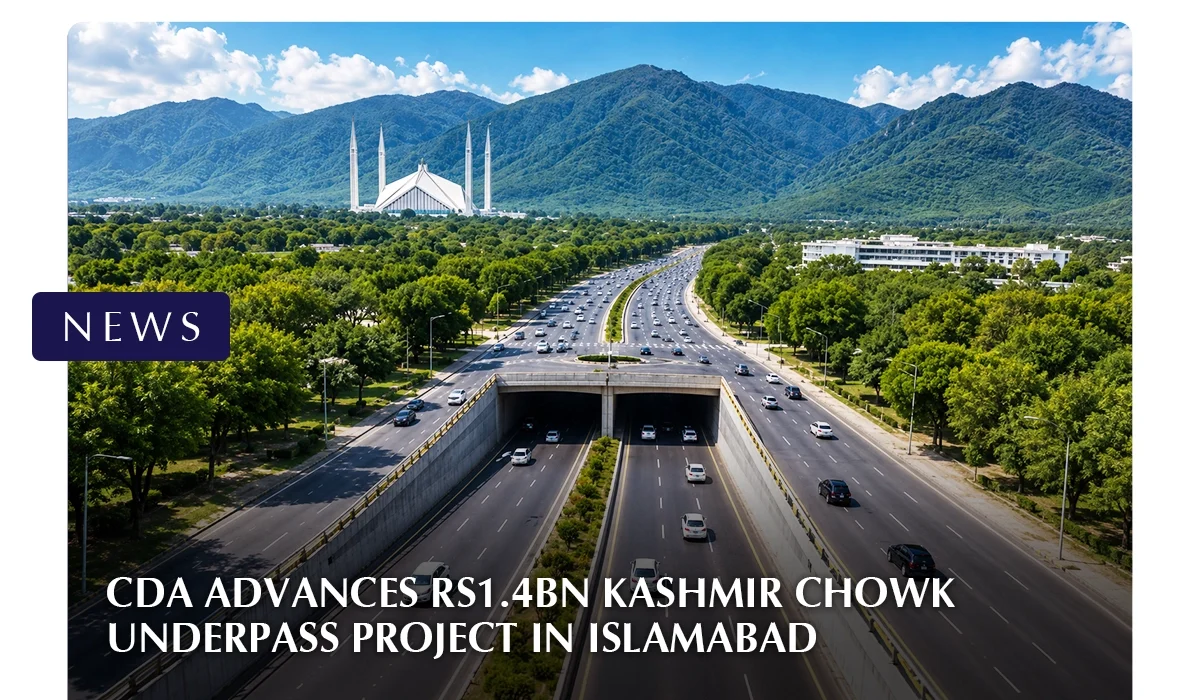
CDA Advances Rs1.4bn Kashmir Chowk Underpass Project in Islamabad

ISLAMABAD: The Capital Development Authority (CDA) has moved forward with plans to construct an underpass at Kashmir Chowk on Murree Road, with the project estimated to cost around Rs1.4 billion.

The proposed underpass, located at Dhokri Chowk near Islamabad Club, is intended to improve traffic movement at the busy intersection. Under the planned arrangement, vehicles travelling from the Serena side towards Rawalpindi will use the underpass, while traffic heading towards Murree will pass over its upper section.

CDA has opened technical bids submitted by Habib Construction Services and M/s Kamran Khan (Kundi Group). During the evaluation process, Kundi Group was declared non-responsive and subsequently filed a grievance with the civic authority. Financial bids will remain unopened until the complaint is decided. Officials expect the matter to be resolved within 15 days.

Separately, CDA is also preparing another underpass at the junction of Faisal Avenue and Margalla Road, where the PC-I is being finalised before the tendering process begins.

The projects form part of CDA’s broader road infrastructure programme aimed at improving traffic flow across Islamabad. Meanwhile, the federally funded 10th Avenue project remains incomplete, with about half of its work still pending despite its original 2024 completion target.

For more real estate news and special reports, visit Chakor.

Source:

CategoriesNews Construction Developments Economy Property Property Laws Real Estate Investment

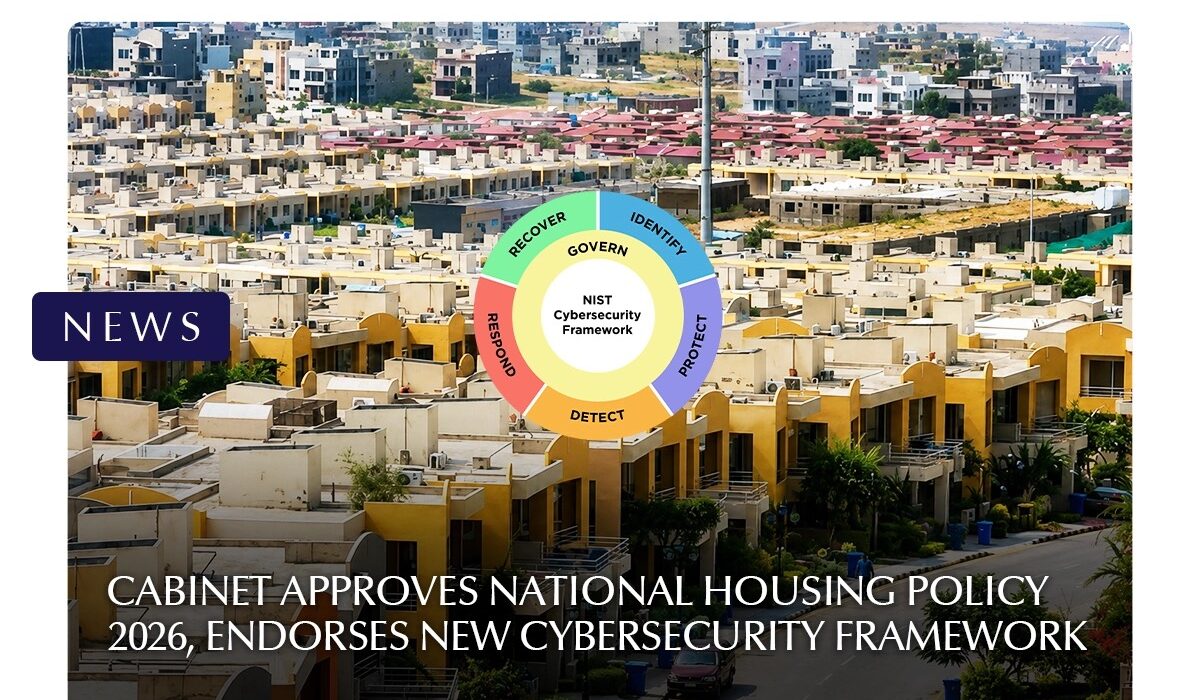
Cabinet Approves National Housing Policy 2026, Endorses New Cybersecurity Framework

ISLAMABAD: The federal cabinet, chaired by Prime Minister Shehbaz Sharif, has approved the National Housing Policy 2026 together with a corresponding implementation plan. Under the policy, housing projects will be required to fully observe zoning regulations, with priority given to vertical construction to improve land-use efficiency. 

Officials noted the policy was drafted with input from local and international experts, along with federal, provincial, and development-sector stakeholders, aiming to ensure sustainable and quality housing nationwide. Energy-efficiency standards have also been folded into the policy framework to align new construction with environmental goals.

The cabinet was additionally briefed on the Apna Ghar housing scheme, revealing that banks have sanctioned loans worth Rs220 billion for prospective homeowners, of which more than Rs32 billion has already been disbursed.

In a separate move, the cabinet approved withdrawing Pakistan’s earlier notice to terminate its 1981 bilateral investment treaty with Sweden, based on a summary presented by the Board of Investment.

On the technology front, the Ministry of Information Technology introduced the draft Pakistan Information Security Framework 2026 (PISF 2026), developed under the CERT Rules 2023. The framework is designed to establish unified baseline cybersecurity standards with centralized oversight. The cabinet approved it as a key policy document and directed its timely implementation.

Further ratifications included proposed amendments to the Pakistan Oil Refining Policy 2023, aimed at upgrading refineries to strengthen energy supply, along with decisions made during recent Economic Coordination Committee and Cabinet Committee on Legislative Cases meetings.

For more real estate news and special reports, visit Chakor.

Source: DAWN

CategoriesNews Economy Property Real Estate Real Estate Investment

Rs. 16.44 Billion Raised as Islamabad Auction Enters Final Day

ISLAMABAD: The Capital Development Authority (CDA) collected Rs. 16.44 billion during the opening two days of its ongoing commercial plot auction at Islamabad’s Jinnah Convention Centre, with a third and final round of bidding still ahead. The first day alone brought in Rs. 13.81 billion, while the second added a further Rs. 2.63 billion to the tally.

Tuesday’s proceedings featured strong demand for agricultural land along Murree Road, where Agro Farm No. 18 sold for Rs. 1.212 billion and Agro Farm No. 17-A brought in Rs. 966 million.

Commercial shop units in the Blue Area Parking Plaza also performed well, with three individual units fetching between roughly Rs. 147 million and Rs. 154 million apiece.

Not every offering found a buyer, however. Two commercial plots in Sector C-13, a site that has remained mired in controversy for nearly two decades, failed to attract meaningful bids despite CDA officials anticipating combined proceeds exceeding Rs. 10 billion.

The sector was originally acquired under the 2007 Land Sharing Policy, but many of the original landowners say they are still waiting to be compensated or resettled.

Affected residents have raised objections to CDA continuing to market land from the sector while their claims remain unresolved. According to landowner accounts, the CDA Board approved a plan in 2023 to compensate eligible families with residential plots in the adjacent Sector C-14, and revenue authorities subsequently completed ownership verification.

Despite this, no allotments have reportedly been issued. The dispute has also drawn intervention from the Islamabad High Court, which ordered CDA to settle outstanding compensation, though claimants say that order has yet to be enforced.

The auction is scheduled to conclude on Thursday, with the authority expressing hope that the final day will generate additional revenue from the sale of remaining commercial properties across the capital.

For more real estate news and special reports, visit Chakor.

Source:

CategoriesNews Economy Investment Real Estate Investment

US Business Delegation Wraps Up Karachi Visit, Reviews SIFC-Backed Investment Projects

KARACHI: A high-level United States business delegation wrapped up a two-day visit to Karachi on Sunday, engaging with Sindh’s provincial leadership to assess investment prospects across multiple sectors under the facilitation of the Special Investment Facilitation Council (SIFC).

On the visit’s second day, delegates held meetings with provincial ministers to review opportunities tied to major development initiatives, including the Bin Qasim Industrial Park and Karachi Industrial Park, alongside other proposed schemes designed to expand industrial and commercial output in the province.

The delegation also received briefings on the Sindh Business One-Stop Shop, Keti Bandar Port, the NED Tech Park, and the proposed Sindh International Financial Centre, with provincial officials detailing each project’s scope and investment potential.

A separate session with the Pakistan Business Council broadened the discussion to capital markets, agriculture, textiles, energy, minerals, and healthcare, among other economic segments.

American delegates conveyed confidence in Pakistan’s strengthening investment climate, citing expanding opportunities across industries. Business representatives further stressed that sustained investor confidence hinges on policy continuity and streamlined regulatory procedures, while crediting SIFC’s coordinating role in advancing ongoing investment efforts.

The visit adds to a string of recent engagements aimed at deepening US-Pakistan commercial ties, with Sindh positioning its industrial parks, port infrastructure, and financial-sector projects as key entry points for foreign capital amid the province’s broader push to court international investors.

For more real estate news and special reports, visit Chakor.

Sources:

Pakistan’s Property Market Gains Momentum
CategoriesNews Economy Property Property Laws Property Taxes Real Estate Real Estate Investment

Pakistan’s Property Market Gains Momentum Amid Tax Cuts and Global Shifts

ISLAMABAD: Pakistan’s real estate sector is witnessing a notable resurgence, with market activity accelerating across major urban centres including Karachi, Lahore, and Islamabad. Industry analysts attribute the renewed interest to a combination of domestic tax relief measures and shifting global economic conditions, prompting both local and overseas investors to reconsider property as a preferred asset class.

At the centre of this shift is a reduction in property transaction taxes, which has lowered the overall cost of buying and selling real estate. This adjustment has made the market more accessible to genuine homebuyers as well as investors seeking stable returns. 

Adding to the momentum, the federal government has proposed abolishing Section 7E, a tax provision long criticised by property stakeholders as an unnecessary financial burden on owners. Should this proposal advance, experts anticipate it could further stimulate transaction volumes in the months ahead.

External factors are also playing a role. Rising uncertainty in the Middle East has reportedly prompted a segment of overseas Pakistanis to reassess their international investment holdings, with many turning attention toward established, well-developed housing projects back home as a comparatively secure option.

The combined effect of these dynamics has been reflected in pricing trends, with residential property values in several key cities climbing by an estimated 10 to 15 percent in recent weeks. Analysts note, however, that this growth is uneven, shaped largely by limited inventory in high-demand locations rather than a uniform market-wide surge.

Looking ahead, real estate professionals are calling for continued reform, particularly simplified taxation procedures and modernised land record systems to sustain investor confidence. 

At the same time, experts continue to urge caution, advising buyers to independently verify ownership documentation, project approvals, and development status before committing funds, rather than basing decisions solely on recent price appreciation.

For more real estate news and special reports, visit Chakor.

Sources:

CategoriesNews Property Real Estate Real Estate Investment Urban Developments & Planning

Apna Ghar Scheme Delivers Rs204bn in Approved Housing Finance

ISLAMABAD: Banks have approved housing finance worth Rs204 billion under the Prime Minister’s Apna Ghar Scheme, with Rs27 billion already disbursed to beneficiaries, a high-level review meeting was informed on Tuesday.

Chairing the meeting, Prime Minister Shehbaz Sharif said the scheme was designed to enable low- and middle-income households to own homes, describing affordable housing as one of the government’s foremost priorities.

Officials briefed the meeting that the Ministry of Housing and Works, together with the State Bank of Pakistan, is conducting weekly reviews to track progress and address bottlenecks in implementation.

The prime minister directed authorities to accelerate work on the scheme and called on public and private sector banks to expand financing support, aiming to widen access to housing loans for eligible families.

He further instructed relevant departments to devise a comprehensive strategy for both vertical and horizontal housing developments under the initiative, emphasising the need for practical and sustainable solutions to meet the demands of a growing population.

Reaffirming the government’s commitment to providing shelter for disadvantaged and middle-income citizens, the prime minister stressed that close coordination among all stakeholders remains essential for the scheme’s timely and successful execution.

The meeting was attended by Federal Minister for Finance and Revenue Muhammad Aurangzeb, Federal Minister for Housing and Works Riaz Pirzada, Minister of State for Finance and Railways Bilal Kayani, and senior government officials.

The Apna Ghar Scheme aims to finance 150,000 homes by June 2027, as part of the government’s broader affordable housing agenda.

For more real estate news and special reports, visit Chakor.

Sources:

CategoriesNews Economy Real Estate Investment

AI to Replace Manual Tax Notices as Pakistan Eyes $750M Eurobond After Panda Bond Success

ISLAMABAD: Pakistan’s tax administration is set to shift toward an artificial intelligence-led engagement model, with human intervention between the tax authority and taxpayers reduced to a minimum, Finance Minister Muhammad Aurangzeb said while addressing a banking summit in Karachi.

The minister noted that Parliament has approved a new tax administration structure under which taxpayer notices will now be issued through AI-led systems, marking a shift from the traditional, human-dependent compliance process.

On external financing, Aurangzeb expressed optimism over Pakistan’s entry into international bond markets, citing the recent Panda Bond issuance as a notable milestone despite the country’s late arrival in China’s capital markets. The bond, launched in mid-May, raised the equivalent of $250 million in yuan and attracted demand exceeding five times its target.

The government is now preparing additional Eurobonds and sukuk, with upcoming instruments structured as dollar-settled, rupee-linked bonds, a first for Pakistan. Requests for proposals have been sent to international investors to gauge pricing and demand.

Following Pakistan’s re-entry into the international bond market after a four-year gap, strong Eurobond demand has created room to raise issuance size to $750 million, the minister said.

On capital markets, Aurangzeb said activity drivers mattered more than headline index figures, citing a growing investor base, including Gen Z participants, and a return to double-digit corporate profitability.

On fiscal policy, he said this year’s budget was formulated for the first time by the Tax Policy Office, now under the Finance Division, with focus on export-led growth through removal of the advance and super taxes.

Pakistan Banks’ Association Chairman Zafar Masood added that the banking sector paid over Rs1 trillion in annual taxes, with agriculture lending up 39 percent, housing lending up 90 percent, and SME lending growth exceeding 111 percent year-on-year.

For more news on real estate and special reports, visit Chakor.

Source: