The Prime Minister Housing Loan Scheme, officially the Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna, offers first-time home buyers in Pakistan loans of up to Rs 10 million. The markup is 5% for the first 10 years. The tenure runs up to 20 years, with a 10% down payment.
Last updated: October 2026
What Is the Prime Minister Housing Loan Scheme?
The Prime Minister Housing Loan Scheme is a government markup subsidy and risk-sharing scheme for affordable housing finance. Its official name is Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. People also call it the PM Apna Ghar scheme or the pm housing loan scheme.
This is a government housing loan scheme, but banks provide the funds. The government pays part of the markup so that borrowers pay a lower rate in the early years. Commercial banks, Islamic banks, microfinance banks, and the House Building Finance Company Limited (HBFCL) participate in the scheme.
Prime Minister Shehbaz Sharif launched the programme on 30 April 2026. According to the State Bank of Pakistan (SBP), the scheme was revised in September 2025. That revision raised the maximum loan to Rs 10 million and set the subsidised rate at 5% for the first 10 years.
Some bank pages still use the earlier name, Mera Pakistan Mera Ghar. This earlier government scheme was introduced in October 2020. If you see that name on a bank website, check the terms listed there against the current programme.
This scheme is for Pakistan. It is not the Indian PMAY scheme.
Key Features of the PM Housing Loan Scheme
| Feature | Details |
| Maximum loan | Up to Rs 10 million through commercial and Islamic banks |
| Microfinance banks | Up to Rs 5 million |
| Markup rate | 5% fixed for the first 10 years |
| After 10 years | 1-year KIBOR + 3% |
| Loan tenure | Up to 20 years, with the subsidy for the first 10 years |
| Financing | 90% from the bank, 10% from the borrower |
| Processing fee | None |
| Early repayment penalty | None |
| House size | Up to 10 marla |
| Flat or apartment size | Up to 1,500 sq ft |
The subsidy covers only the first 10 years. If you take a 20-year loan, the bank charges a market-based rate in the last 10 years. That rate is linked to the 1-year KIBOR.
Who Is Eligible for the PM Housing Loan Scheme?
The eligibility rules are simple at the national level. Banks then add their own checks on income, age and documents.
Basic Eligibility
- You must be a Pakistani citizen with a valid CNIC. Overseas Pakistanis can apply with a NICOP.
- You must be a first-time homeowner.
- You must not own any housing unit in your name.
Who Can Apply?
The SBP says people from all professions can apply. This includes salaried people with documented income and people without formal payslips. Overseas Pakistanis are also eligible.
Age Limits
The scheme itself does not set an age limit. Each bank sets its own. As examples, BankIslami lists 25 to 60 years for salaried applicants and 25 to 65 years for self-employed applicants. JS Bank lists 23 to 60 years for salaried applicants and 21 to 75 years for self-employed applicants. Check with your bank before you apply.
Income Requirements
Zameen reports a minimum income of Rs 25,000 per month for the main applicant and Rs 20,000 for a co-applicant. Some banks ask for more. For example, Bank of Khyber lists Rs 35,000 as the minimum net monthly income.
Co-Applicants
You can apply with up to three other people to meet the repayment requirement. Older applicants can also apply together with earning family members.
Government Employees
Government employees can apply for this government housing loan like other salaried applicants. Contractual government employees usually need at least three years of service.
Salaried employees generally need at least two years of employment, and self-employed applicants need three years of business history. These rules vary by bank.
Overseas Pakistanis
Non-resident Pakistanis with a valid NICOP can apply. Banks such as Bank Alfalah list both residents and non-residents as eligible.
What Can You Buy or Build? Prime Minister Housing Loan Scheme
The Prime Minister’s house loan scheme can finance:
- The purchase of a house or flat
- The construction of a house on a plot you already own
- The purchase of a plot and construction of a house on it
- The purchase of a unit in an under-construction project
The scheme covers houses of up to 10 marla and flats of up to 1,500 sq ft. It is for residential use only. It does not cover investment or rental properties.
The bank values the property through its own approved evaluator. This is separate from the FBR valuation rate in Pakistan, which is used for property taxes.
For construction, banks usually release funds in phases tied to on-site progress.
Markup Rate, EMI and the Cost of Your Loan
The first 10 years carry a fixed 5% rate. This keeps the monthly instalment low. Islamic banks call it a rental or profit rate. For example, Meezan Bank lists a fixed rental rate of 5% for the first 10 years.
Askari Bank publishes a sample table for a financing amount of Rs 10 lakh (Rs 1,000,000):
| Tenure | Monthly payment (first 10 years) |
| 10 years | Rs 10,607 |
| 15 years | Rs 7,908 |
| 20 years | Rs 6,600 |
Using the same 5% rate, you can estimate payments for other loan sizes. These are approximate figures for the first 10 years only:
| Loan amount | 10 years | 15 years | 20 years |
| Rs 5 lakh | about Rs 5,300 | about Rs 3,950 | about Rs 3,300 |
| Rs 25 lakh | about Rs 26,500 | about Rs 19,800 | about Rs 16,500 |
| Rs 50 lakh | about Rs 53,000 | about Rs 39,500 | about Rs 33,000 |
| Rs 1 crore | about Rs 106,000 | about Rs 79,000 | about Rs 66,000 |
For example, a Rs 1 crore loan over 20 years works out to about Rs 66,000 per month during the first 10 years. After that, the rate moves to 1-year KIBOR + 3%. Your instalment can then change.
The scheme has no processing fee and no early repayment penalty. You can pay the loan off early without a penalty. Property purchase taxes are separate from the loan. For example, buyers pay advance tax under Section 236K.
For exact figures, use the Prime Minister Housing Loan Scheme calculator on your bank’s website. For example, Bank Alfalah lists a calculator for the programme.
How Much Loan Can You Get on Your Salary?
The prime minister housing loan you qualify for depends on your income. Banks check your debt burden ratio (DBR). Zameen reports that the DBR must not exceed 33% of your net monthly income. This means your total monthly loan payments should stay within about one-third of your income.
Here is a simple estimate for a 20-year loan at 5%, assuming you have no other loans:
| Net monthly income | 33% available for the instalment | Approximate loan size |
| Rs 25,000 | Rs 8,250 | About Rs 12.5 lakh |
| Rs 35,000 | Rs 11,550 | About Rs 17.5 lakh |
| Rs 50,000 | Rs 16,500 | About Rs 25 lakh |
| Rs 100,000 | Rs 33,000 | About Rs 50 lakh |
These are estimates, not bank offers. Each bank makes its own assessment. Existing loans reduce the amount you can borrow. Adding a co-applicant can raise it.
Documents Required – Prime Minister Housing Loan Scheme
The documents for the PM house loan scheme depend on the bank and whether you are salaried, self-employed, or have informal income. For a pm housing loan, banks commonly ask for:
- Valid CNIC (front and back), or NICOP for overseas Pakistanis
- Recent passport-size photograph
- Employment certificate and salary slip, for salaried applicants
- Business documents, for self-employed applicants
- Bank statements, usually for the last six months to a year
- Property documents, if you already own the plot
- Utility bills
Banks also check your credit history through the Electronic Credit Information Bureau (ECIB). A clean record helps your application.
How to Apply for the Prime Minister Housing Loan Scheme?
There are two ways to apply. You can apply through the official online portal or at a participating bank.
Prime Minister House Loan Scheme in Pakistan Online Apply: Step-by-Step
Many readers search for the Prime Minister Housing Loan Scheme apply online process. The official portal is apnaghar.gov.pk. Follow these steps:
- Check that you meet the eligibility rules above.
- Gather your documents, such as your CNIC, photo, employment certificate, salary slip and six-month bank statement.
- Open the official portal at apnaghar.gov.pk and submit your application details.
- Upload your documents when the form prompts you.
- Wait for the bank to contact you. Some banks, such as Bank Alfalah, state that a representative will contact you within three working days of your request.
- Complete the bank’s checks, including property valuation and credit history review.
Applying Directly at a Participating Bank
You can also apply directly at a participating bank. Visit the branch, ask for the Wazir-e-Azam Apna Ghar Program and submit your documents. Some banks, such as Allied Bank, state that their branches are designated to receive and process applications. Askari Bank says it accepts applications at every branch.
What Happens After You Apply? Prime Minister Housing Loan Scheme
The bank reviews your income and credit record. It also values the property through its approved evaluator. If approved, you pay the 10% down payment, and the bank finances the remaining 90%.
The government has announced SBP reforms aimed at reducing approval time to about 15 days, according to Profit. Once the bank approves the loan, the property transfer must be registered. See this guide to property registration in Pakistan for the steps and charges.
Be careful with agents who promise to speed up your file. The process runs through banks. You can handle it yourself.
Which Banks Offer a House Loan in Pakistan Under This Scheme?
Commercial banks, Islamic banks, microfinance banks, and HBFCL all participate. Banks that publish the scheme on their websites include:
| Type | Banks |
| Conventional | Allied Bank, Askari Bank, Bank Alfalah, Bank AL Habib, Bank of Khyber, MCB Bank, National Bank of Pakistan, Soneri Bank, JS Bank |
| Islamic | Meezan Bank, BankIslami, and the Islamic windows of other banks |
| Public sector | House Building Finance Company Limited (HBFCL) |
The scheme’s main terms apply across participating institutions. These include the 5% rate, 90:10 split and Rs 10 million limit. Banks differ in income requirements, age limits, documents and service. Compare these points when choosing where to apply for a house loan in Pakistan. Choose between conventional and Islamic financing based on your own preference.
Applications So Far: Prime Minister Housing Loan Scheme
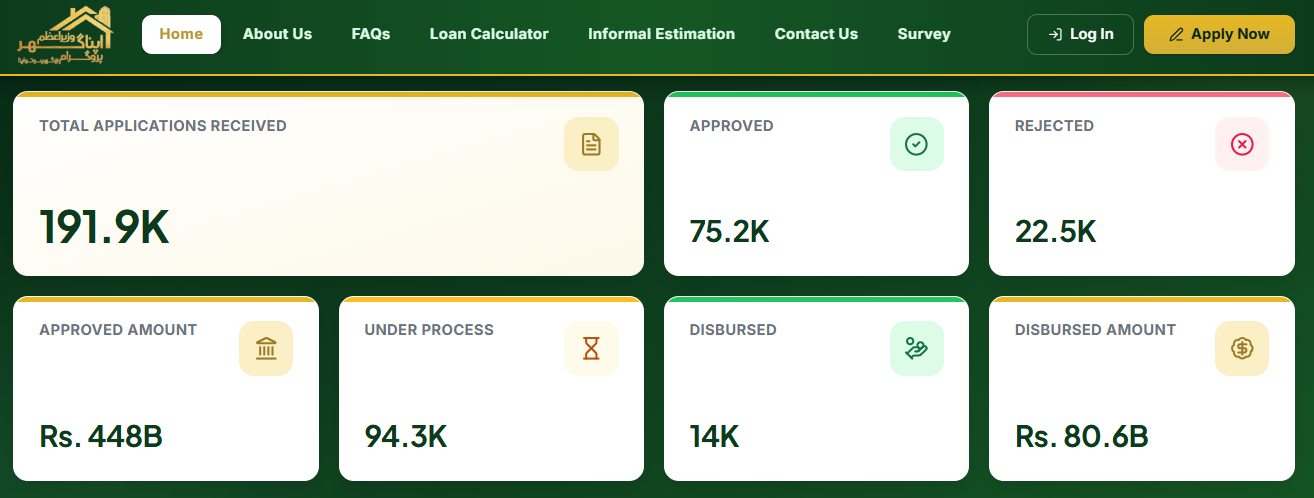
The SBP shared figures at a workshop in July 2026. Banks had received 107,000 applications since March 2025. Nearly 80% came after the September 2025 revision. More than 27,000 applications had been approved and 13,000 rejected.
By 30 June 2026, banks had disbursed more than 6,000 loans worth Rs 26 billion. The average loan was Rs 4.8 million.
The federal budget for FY2026-27 sets aside Rs 71 billion to subsidise the loans. The government aims to finance 150,000 homes by June 2027.
Tips to Improve Your Chances of Approval
- Check your credit record before you apply. Banks review your ECIB history.
- Keep your total monthly loan payments within the debt burden limit.
- Add a co-applicant if your income alone is not enough.
- Keep your income and property documents complete and up to date.
- Choose a property within the size limits: up to 10 marla for a house and 1,500 sq ft for a flat.
- Apply through the portal or directly at a bank branch, not through unofficial agents.
Is the Prime Minister Housing Loan Scheme Worth It?
The scheme has clear benefits. The 5% rate for 10 years is low. There is no processing fee and no early repayment penalty. The 10% down payment is lower than what many buyers expect.
There are other points to weigh. The rate changes after year 10. The size limits may not suit every buyer. The scheme covers residential use only, and the bank decides how much it will lend based on your income. Read your bank’s key fact statement before you sign. Budget for taxes and fees on top of the 10% down payment. A property tax calculator can help you estimate them.
For first-time buyers in Pakistan, the scheme is a practical way to move from renting to owning.
FAQs – Prime Minister Housing Loan Scheme
What are the eligibility criteria for the Prime Minister housing loan scheme?
You must be a Pakistani citizen with a valid CNIC, or an overseas Pakistani with a NICOP. You must be a first-time homeowner and must not own any housing unit in your name. Banks set their own income, age and employment rules.
How to apply for the government-backed home loan scheme?
You can apply through the official portal at apnaghar.gov.pk or at a participating bank. Prepare your CNIC, photo, income proof and bank statements. The bank then checks your income, credit history, and the property before approving your application.
Can I apply for the PM Apna Ghar loan scheme online?
Yes. The official portal at apnaghar.gov.pk accepts applications, and some banks also offer online application forms. Banks may ask you to visit a branch later to complete the process.
How to apply for the PM loan scheme in 2026?
Confirm your eligibility, gather your documents, then apply through the portal or a participating bank. Keep your documents ready so the bank can complete valuation and credit checks quickly.
Who is eligible for the PM Apna Ghar scheme?
First-time homeowners with a valid CNIC or NICOP who do not own a house or flat in their name. The SBP says applicants from all professions can apply, including those without formal payslips.
Can I apply for Mera Pakistan Mera Ghar online in 2026?
Some banks still use the Mera Pakistan Mera Ghar name for their housing finance pages. The current government programme is Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. Apply through the official portal or a participating bank.
What are the requirements to qualify for a home loan under the scheme?
You need a valid CNIC, proof of income, bank statements and a property that meets the size limits. Banks also check your credit history and debt-to-income ratio.
What is the EMI for a 1 crore home loan for 20 years?
At the scheme’s 5% rate, a Rs 1 crore loan over 20 years costs about Rs 66,000 per month during the first 10 years. After that, the rate becomes 1-year KIBOR + 3% and the instalment can change.
Which bank is best for a house loan in Pakistan?
The scheme’s core terms are the same across participating banks. Banks differ in income and age rules, documents, branch access and service. Compare these points and decide between conventional and Islamic financing.
What is Meezan Bank’s house loan scheme?
Meezan Bank offers the Wazir-e-Azam Apna Ghar Program as an Islamic financing option. It offers a fixed rental rate of 5% for the first 10 years, a tenure of up to 20 years, and financing up to Rs 10 million.
Can I get a 0% interest loan in Pakistan?
Not under this scheme. The government subsidy lowers the rate to 5% for the first 10 years. Islamic banks charge a rental or profit rate instead of interest.
How much loan can I get with a 35,000 salary?
It depends on the bank. As an estimate, a debt burden limit of 33% leaves about Rs 11,550 per month for the instalment. At the scheme’s 5% rate over 20 years, that supports a loan of about Rs 17.5 lakh. A co-applicant can increase the amount.
Is the Prime Minister housing loan scheme a personal loan?
No. It is housing finance. You use it to buy or build a house or flat, and the property is the loan’s purpose.
Conclusion
The pm housing loan scheme and the wider government housing loan scheme depend on bank approval, so check your income, credit history and documents first. Visit the official portal at apnaghar.gov.pk or your nearest participating bank to apply.
Once you have your finance in place, explore the latest residential and commercial developments from Chakor, Pakistan’s leading real estate developer.
Sources:
- Wazir-e-Azam Apna Ghar Program (official portal)
- HBFC circular on the scheme
- State Bank of Pakistan
- Business Recorder

BBC-featured Content Specialist with a sharp eye for search intent and a proven ability to turn content into a growth engine. I leverage cutting-edge digital marketing tools to craft strategies that fuel organic traffic, amplify brand growth, and own the local SEO landscape, particularly across the competitive real estate market. I help brands dominate search rankings and convert visibility into measurable business success.
